
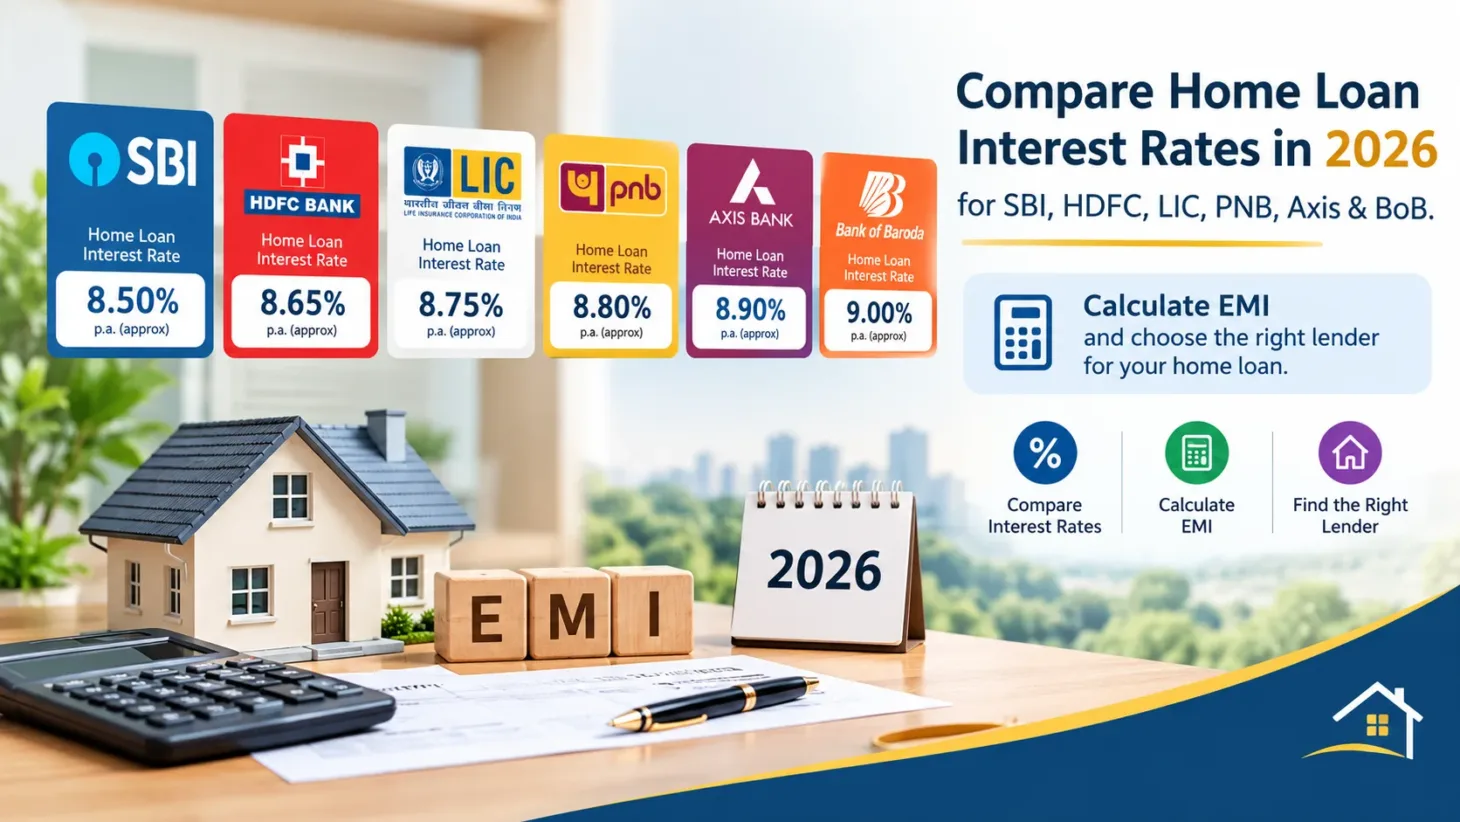
Home loan interest rates in 2026 vary widely by lender, credit score, loan amount, and borrower profile. For a strong borrower, leading lenders such as SBI, HDFC Bank, LIC Housing Finance, PNB, Axis Bank, Bank of Baroda, and Canara Bank offer competitive floating-rate options. However, the lowest advertised rate isn’t always the lowest-cost loan.
Buying a home is a major financial decision. Therefore, even a small difference in the home loan interest rate can change your EMI and total interest by lakhs of rupees.
So, which lender should you choose in 2026?
Let’s compare the major options and understand calculating home loan EMI with simple examples.
Home Loan Interest Rate All Bank: 2026 Comparison
The following rates are indicative starting rates/ranges available around September 2026. Banks can change their rates, and your final rate may be different based on your CIBIL score, income, loan size, property, and other factors.
| Bank / Lender | Indicative 2026 Rate | Best Known For |
|---|---|---|
| SBI Home Loan | Around 7.25% onwards* | Large PSU network |
| HDFC Bank Home Loan | Around 7.9% onwards | Digital processing & private banking |
| LIC Housing Finance | Around 7.15%–7.5% onwards* | Housing-focused lending |
| PNB Home Loan | Around 7.25% onwards* | PSU pricing |
| Axis Bank Home Loan | Around 8.35% onwards | Private-bank service |
| Bank of Baroda Home Loan | Around 7.45% onwards | Competitive PSU rates |
| Canara Bank Home Loan | Around 7.4% onwards | PSU housing finance |
*Published rates can vary by product, CIBIL score, loan amount, borrower category, and current lender offers. SBI’s published rate structure is credit-score linked, while PNB’s current official page shows housing-loan rates starting from 7.25%. LIC Housing Finance also publishes rates based on CIBIL score and loan slab.
Important: Don’t compare only the “starting rate.” Compare the rate actually offered to you.
SBI Home Loan Interest Rate 2026
The SBI home loan interest rate is linked to the borrower’s credit profile and the applicable benchmark.
SBI’s published home-loan structure shows different rates according to CIBIL score. It also offers concessions in certain cases, including eligible women borrowers.
Why consider SBI housing loan interest rate?
SBI can be attractive if you want:
- A large branch network
- A well-known public-sector lender
- Competitive floating rates
- Long repayment periods
- Multiple home-loan products
Your State Bank of India home loan interest rate should still be checked against the exact sanction letter before you make a final decision.
HDFC Home Loan Interest Rate 2026
The HDFC home loan interest rate depends on several borrower and property factors.
HDFC Bank’s lending rates and benchmark rates can change over time. In September 2026, HDFC Bank reduced several MCLR rates by 5–10 basis points, although an MCLR change should not be confused with the exact rate offered on every new home loan.
Is HDFC Bank home loan a good option?
It can be useful for borrowers who value:
- Private-bank service
- Digital application processes
- Flexible loan options
- Strong presence across major cities
However, always ask for the HDFC Bank home loan sanction rate rather than relying only on an advertised starting rate.
LIC Home Loan Interest Rate 2026
The LIC home loan interest rate is offered through LIC Housing Finance.
LIC HFL currently publishes rate slabs based on CIBIL score and loan amount. For example, its published table shows lower rates for borrowers with very high CIBIL scores, while rates rise as the credit score falls.
LIC Housing Finance interest rate example
According to LIC Housing Finance’s published information, borrowers with a CIBIL score of 825 or above can get rates starting at 7.15% for loans up to ₹5 crore under the listed home-loan slab.
This shows why your LIC housing finance interest rate may be very different from another applicant’s rate.
PNB Home Loan Interest Rate 2026
The PNB home loan interest rate is strongly linked to the borrower’s CIBIL score, loan amount, LTV ratio, and loan type.
PNB’s current official housing-loan page shows rates starting from 7.25% per annum for eligible borrowers. Its published table also shows higher rates for lower credit scores.
Why compare PNB housing loan interest rate?
PNB may suit borrowers looking for:
- A public-sector bank
- Competitive floating rates
- Different loan structures
- Traditional branch-based support
If your CIBIL score is high, ask PNB for its best applicable rate before accepting another lender’s offer.
Axis Bank Home Loan Interest Rate 2026
The Axis home loan interest rate generally depends on the applicant’s credit profile and the lender’s risk assessment.
Current market comparisons place Axis Bank’s advertised home-loan rates above some leading PSU lenders, although the exact offer depends on the borrower.
When should you consider Axis Bank?
Axis Bank may be worth comparing if you prefer:
- Private-bank service
- Digital processes
- Relationship-based banking
- Competitive offers for strong borrowers
Don’t assume that a higher starting rate automatically means a more expensive loan. Compare the final sanctioned rate plus fees.
Bank of Baroda Home Loan Interest Rate 2026
The Bank of Baroda home loan interest rate remains competitive among public-sector lenders.
Current September 2026 market comparisons place Bank of Baroda rates around 7.45% onwards, although the actual rate depends on borrower and loan characteristics.
Bank of Baroda housing loan interest rate: What affects it?
Your rate can depend on:
- CIBIL score
- Loan amount
- Loan-to-value ratio
- Income profile
- Property type
- Employment status
- Existing relationship with the bank
Therefore, get a written quote before comparing it with SBI or PNB.
Canara Bank Home Loan Interest Rate 2026
The Canara home loan interest rate is another option worth checking, particularly for borrowers comparing public-sector lenders.
Recent September 2026 market data puts Canara Bank among the lenders offering competitive starting rates.
A small rate difference can matter over a 15–30-year loan. So, compare Canara Bank with SBI, PNB and Bank of Baroda instead of choosing only by brand name.
Which Bank Has the Lowest Home Loan Interest Rate in 2026?
There isn’t one lender that will always give everyone the lowest rate.
For example, current published comparisons show starting rates can be around the low-7% range for some lenders, while other lenders start closer to 8% or higher.
Your lowest home loan interest rate depends mainly on:
- CIBIL score
- Monthly income
- Employment type
- Loan amount
- Loan-to-value ratio
- Property documents
- Existing banking relationship
- Current lender offers
Quick answer: If you have a strong credit profile, compare at least three written loan offers before choosing.
How Is Home Loan EMI Calculated?
Your EMI depends on three main numbers:
- P = Principal loan amount
- R = Monthly interest rate
- N = Number of monthly instalments
The standard EMI formula is:
EMI = P × R × (1 + R)ⁿ ÷ [(1 + R)ⁿ – 1]
It looks complicated, but you don’t need to calculate it manually.
Example: ₹50 Lakh Home Loan
Suppose you borrow:
- Loan amount: ₹50 lakh
- Interest rate: 8%
- Tenure: 20 years
Your approximate EMI would be ₹41,822 per month.
Over 20 years, total repayment would be about ₹1 crore, including approximately ₹50 lakh in interest.
This is why the interest rate and tenure matter so much.
EMI Comparison at Different Interest Rates
Let’s compare a ₹50 lakh loan for 20 years.
| Interest Rate | Approx. Monthly EMI |
|---|---|
| 7.25% | ₹39,519 |
| 7.50% | ₹40,280 |
| 8.00% | ₹41,822 |
| 8.50% | ₹43,391 |
| 9.00% | ₹44,986 |
The difference between 7.25% and 9% is roughly ₹5,500 per month.
That’s why comparing your actual offer matters.
How Does Loan Tenure Affect Your EMI?
A longer tenure reduces your monthly EMI. However, it can increase the total interest you pay.
For example, consider a ₹50 lakh loan at 8%:
- 15 years: EMI ≈ ₹47,779
- 20 years: EMI ≈ ₹41,822
- 25 years: EMI ≈ ₹38,591
- 30 years: EMI ≈ ₹36,688
A 30-year loan looks easier every month. Yet you’ll pay interest for a much longer period.
What Is the Best Home Loan Tenure?
Choose the shortest tenure you can comfortably afford.
However, don’t make your EMI so high that it damages your monthly cash flow. A balanced approach is usually better than choosing the shortest possible tenure.
What CIBIL Score Is Needed for a Home Loan?
There isn’t one universal minimum score for every lender.
Generally, a higher CIBIL score can improve your chances of approval and help you negotiate a better interest rate. LIC Housing Finance and PNB, for example, publish different rates based on credit-score bands.
Before applying, check your credit report for:
- Incorrect outstanding loans
- Missed-payment records
- Incorrect personal information
- Credit accounts that should be closed
Fixed vs Floating Home Loan Interest Rate
Most home buyers compare floating-rate loans because the rate can change during the loan period.
Floating rate
Your interest rate can move up or down according to the applicable benchmark and lender’s spread.
Advantage: You may benefit when lending rates fall.
Risk: Your EMI or loan tenure can increase when rates rise.
Fixed rate
The interest rate remains fixed for the agreed period or under the lender’s fixed-rate terms.
Advantage: Easier financial planning.
Risk: You may not benefit immediately if market rates fall.
For a long-term home loan, understand the reset rules before signing.
What Should You Compare Besides the Interest Rate?
The cheapest advertised rate isn’t always the cheapest loan.
Before choosing a lender, compare:
- Interest rate
- Processing fee
- Legal and technical charges
- Prepayment rules
- Conversion or switching charges
- Loan tenure
- Benchmark and reset frequency
- Insurance requirements
- Late-payment charges
- Customer service
For example, SBI’s published home-loan structure includes different premiums and concessions based on borrower circumstances.
So, ask for the Key Facts Statement and complete cost details before accepting the offer.
How to Get a Lower Home Loan Interest Rate
You can improve your chances with a few simple steps.
1. Improve your CIBIL score
Pay existing EMIs and credit-card bills on time.
2. Keep your debt under control
A lower existing debt burden can strengthen your application.
3. Make a larger down payment
A lower loan-to-value ratio can reduce the lender’s risk.
4. Compare multiple lenders
Get written offers from at least three lenders.
5. Negotiate
If another bank offers you a better rate, ask your preferred lender to match it.
6. Consider a co-applicant
A financially strong co-applicant may improve eligibility, depending on the lender’s policy.
Should You Choose SBI, HDFC, LIC, PNB, Axis or Bank of Baroda?
There’s no single winner for every buyer.
SBI may appeal to borrowers who want a large PSU bank network. HDFC Bank and Axis Bank may appeal to people who prefer private-bank services.
LIC Housing Finance, PNB and Bank of Baroda are also worth comparing, especially if their final sanctioned rate is lower for your profile.
The smart approach is simple: compare the actual loan offer, not just the advertisement.
Home Loan for Buying a Duplex or Triplex in Bhopal
If you’re planning to buy a duplex or triplex in Bhopal, don’t look only at the property’s purchase price.
Also calculate:
- Down payment
- Home loan amount
- Monthly EMI
- Registration and stamp-duty costs
- Interior budget
- Maintenance expenses
- Emergency savings
For a premium independent home, keeping enough cash reserves after the purchase is just as important as getting a low interest rate.
Final Verdict: Which Home Loan Is Best in 2026?
The best home loan in 2026 is the one that gives you a competitive interest rate, manageable EMI, reasonable fees and clear terms.
SBI, HDFC Bank, LIC Housing Finance, PNB, Axis Bank, Bank of Baroda and Canara Bank all deserve comparison. However, your CIBIL score and financial profile can change the final offer significantly.
Before signing, ask every lender for the final interest rate, EMI, total interest, processing charges and prepayment terms in writing.
Remember: A difference of even 0.50% can become a significant amount over a 20–30-year loan.
Frequently Asked Questions
What is the current home loan interest rate in India in 2026?
Home loan rates in 2026 vary by lender and borrower profile. Current market comparisons show some lenders starting in the low-7% range, while others are above 8%.
Which bank has the lowest home loan interest rate in 2026?
There is no single lowest-rate bank for every borrower. SBI, LIC Housing Finance, PNB, Bank of Baroda and Canara Bank can have competitive starting rates, but your final offer depends on your credit score and other factors.
What is the SBI home loan interest rate in 2026?
SBI’s home-loan pricing is linked to borrower credit score and applicable benchmark rates. Its published structure shows different effective rates for different CIBIL bands, so applicants should check the rate offered for their individual profile.
Is HDFC home loan interest rate lower than SBI?
Not necessarily. HDFC Bank and SBI use different pricing structures, and the final rate depends on the applicant. Compare the written sanction offers instead of comparing only the starting rates.
How much EMI is required for a ₹50 lakh home loan?
At 8% interest for 20 years, a ₹50 lakh home loan has an approximate EMI of ₹41,822 per month. The actual EMI will change if the interest rate or tenure changes.
Can I reduce my home loan EMI?
Yes. You can reduce EMI by getting a lower interest rate, increasing the loan tenure, making a larger down payment, or refinancing when a better offer is available. However, increasing the tenure can increase your total interest cost.

Add comment